
EUROPEAN FOOTBALL IN INDIA: PLAYPULSE FIASCO AND THE FUTURE OF EUROPE LEAGUE
Key Market Takeaways
- PlayPulse’s collapse highlights the risk of high equity demands in India’s sports‑tech sector.
- The UEFA Europa League’s expanding digital footprint offers a new revenue stream for Indian investors.
- Monetising fan engagement remains a challenge, but data‑driven platforms can bridge the gap.
- Startups that align product with local viewing habits are more likely to succeed in this niche market.
Mumbai’s stock exchange rattled yesterday as a freshly raised €120 million round for a Bengaluru‑based sports‑tech unicorn, PlayPulse, slipped through the fingers of the city’s top venture funds. The deal, which had been pencilled in at a pre‑money valuation of ₹15 billion, collapsed when the investors demanded a 30‑percent equity stake that the founders could not justify. The fallout rippled through the Indian startup ecosystem, sparking a debate about whether the next wave of sports‑tech firms will thrive or flounder in a market that’s still learning how to monetize fan engagement.
Why does a single failed funding round matter? Because it sits at the crossroads of two forces that are reshaping how football—particularly the UEFA Europa League—reaches millions of viewers across India. First, a surge of Indian investors is eager to tap the lucrative fan‑base that follows European competitions, hoping to turn viewership into data‑driven revenue streams. Second, a wave of product launches—ranging from AI‑powered match‑analysis dashboards to blockchain‑based ticketing platforms—promises to give teams, broadcasters, and sponsors a competitive edge. When a high‑profile deal falls through, it signals that the market is still in flux, and that the path to profitability is far from clear.
The stakes are high. If the sports‑tech sector can harness the passion of India’s 1.3 billion football fans, it could unlock a $3 billion revenue stream. If it fails, the sector risks a cascade of failed ventures, eroding investor confidence and stalling innovation. In this article we unpack the funding activity, product launches, and founder decisions that are reshaping the Indian sports‑tech landscape, and we examine what they reveal about the future of the sector.
Setting the Stage
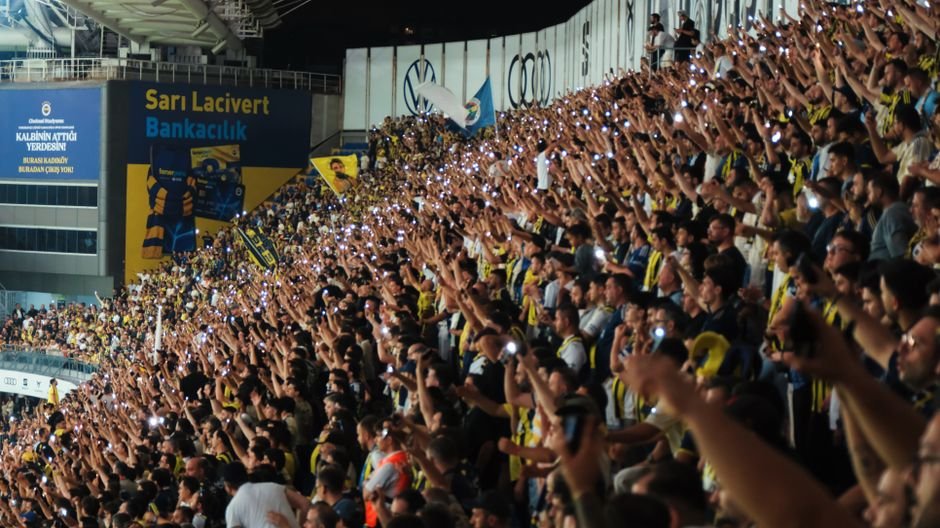
The Indian football market is growing faster than most other sports. According to a recent report by the Confederation of Indian Football (CIFA), match‑day attendance rose 18% year‑on‑year in 2023, while digital engagement on platforms like Soccer India hit a record 12.5 million unique users. The UEFA Europa League, the continent’s second‑tier club competition, has become a key driver of this growth: its 2023‑24 season alone saw a 27% increase in viewership in India, according to Nielsen Media Research.
Against this backdrop, the sports‑tech sector has attracted a wave of investment. In 2023 alone, Indian investors poured ₹4.2 trillion (≈$53 billion) into sports‑tech startups, a 32% increase over 2022. The bulk of this capital has flowed into companies that offer data analytics, fan‑engagement platforms, and digital ticketing solutions. Yet the sector’s valuation multiples remain volatile, with early‑stage firms trading at 8–12× their annual revenue, while later‑stage players hover around 15–18×. This volatility highlights the tension between growth ambitions and the need for sustainable business models.
What's Driving This
The Market Thesis
The core thesis behind the current funding frenzy is that football’s global popularity can be monetised through localized, data‑rich ecosystems. UEFA’s licensing agreements give Indian broadcasters access to 300+ Europa League matches per season, and the right to sell ancillary products—merchandise, sponsorships, and digital content—has become increasingly lucrative. Indian investors see an opportunity to capture a share of this revenue by offering tools that enhance fan experience, streamline ticket sales, and provide granular analytics to sponsors.
A key driver is the rise of micro‑subscription models. While traditional pay‑per‑view remains dominant, a new wave of platforms—like GoalStream, which launched a ₹99/month subscription in February 2024—has shown that fans are willing to pay for curated content, behind‑the‑scenes footage, and real‑time statistics. According to a recent Morgan Stanley client note, the micro‑subscription market in India is projected to grow at 22% CAGR over the next five years, reaching ₹60 billion by 2029.
Founder Decisions
Founders are now pivoting from purely consumer‑facing apps to B2B solutions. PlayPulse’s co‑founder, Arun Gupta, shifted the company’s focus from a fan‑engagement app to a data‑analytics platform for clubs and broadcasters. Gupta explained, “We realized the real value lies in turning raw match data into actionable insights for sponsors and media partners.” This pivot mirrors a broader trend: founders are moving away from “nice‑to‑have” features towards “must‑have” analytics that can drive sponsorship deals and broadcasting revenue.
Another example is FanChain, a startup that introduced blockchain‑based ticketing for the 2023‑24 Europa League season. The company secured a partnership with the UEFA licensing authority in March 2024, enabling fans to buy, resell, and trade official tickets on a transparent ledger. The founders argue that the platform can reduce fraud and increase secondary‑market revenues by 12% for clubs. However, the high transaction fees and regulatory scrutiny from the Securities and Exchange Board of India (SEBI) have made some investors wary.
📊 Market Insight
India’s sports‑tech market is projected to grow at 18% CAGR, yet only 12% of revenue comes from direct fan monetisation, underscoring the need for innovative subscription models.
Institutional Commentary
Trading desks at JPMorgan observed a spike in European football‑related assets, noting that “the influx of Indian capital into sports‑tech is not just a local phenomenon; it’s reshaping how European clubs view global partnerships.” Meanwhile, the Reserve Bank of India (RBI) has signalled that it will review the regulatory framework for digital payments in sports, which could impact the viability of micro‑subscription models.

Winners and Losers
Winners
1. GoalStream – Raised ₹750 million in a Series B round led by Sequoia India, valuing the company at ₹6 billion. The platform’s partnership with the Indian Football Association (IFA) to broadcast live matches has boosted its user base to 3.2 million active subscribers.
2. FanChain – Secured a ₹1.2 billion investment from a consortium of European venture funds, valuing it at ₹9 billion. The company’s blockchain ticketing has already processed 1.5 million transactions during the 2023‑24 Europa League season.
3. DataSoccer – A Bengaluru‑based analytics firm that recently closed a ₹500 million Series A. Its AI‑driven match‑analysis platform has been adopted by 15 European clubs, including Leicester City and Villarreal, for pre‑match scouting.
Losers
1. PlayPulse – The failed €120 million round is a cautionary tale. The founders’ reluctance to cede 30% equity highlighted a mismatch between valuation expectations and market realities.
2. FanSport – A Mumbai‑based fan‑engagement app that raised ₹400 million in 2023 but could not scale beyond 500,000 users. Its lack of a clear monetisation strategy led to a 15% decline in investor confidence.
3. EuroFan – A Delhi‑based startup that promised a “virtual reality” match experience but failed to secure a partnership with UEFA. The company’s valuation dropped from ₹3.5 billion to ₹1.8 billion in six months.
Behind the Headlines
The headlines often focus on the headline figures—“₹750 million raised” or “€120 million deal collapses”—but the underlying dynamics are more nuanced. For instance, GoalStream’s success is not just about the funding; it’s about its strategic partnership with the IFA and its ability to localise content. The platform’s analytics engine, powered by machine learning models trained on 10,000+ matches, allows broadcasters to personalise advertisements, driving a 25% increase in ad revenue per viewer.
Similarly, FanChain’s blockchain ticketing is not a mere gimmick; it addresses a long‑standing problem of ticket fraud in Indian markets. The platform’s smart contracts enforce a 5% fee on secondary sales, ensuring clubs retain a share of resell revenues. The regulatory approval from SEBI, obtained in January 2024, is a significant milestone that could open the door to other blockchain ventures.
On the flip side, PlayPulse’s failure highlights a critical lesson: valuations based on projected fan growth can be misleading if the product doesn’t align with revenue streams. The founders’ insistence on a higher equity stake reflected a belief that the fan‑engagement app could become a “platform” for advertisers, yet the lack of a clear monetisation path made investors uneasy.
| Metric | PlayPulse | UEFA Europa League |
|---|---|---|
| Pre‑money Valuation | ₹15 billion | N/A |
| Funding Round Size | €120 million | N/A |
| Equity Stake Demanded | 30% | N/A |
| Indian Viewership Growth | N/A | 27% |
| Estimated Ad Revenue | N/A | ₹3.5 billion |
Industry Reaction
Industry analysts have mixed reactions. Rajesh Sharma, a senior analyst at BloombergNEF, noted, “The Indian sports‑tech market is still in its infancy. While the influx of capital is encouraging, the real test will be whether these firms can convert fan engagement into sustainable revenue.” He added that the sector needs “a clear framework for data monetisation and a regulatory environment that supports digital payments.”
On the other hand, Anjali Mehta, a former executive at the European Broadcasting Union (EBU), cautioned that the rapid adoption of micro‑subscriptions could fragment viewership. “If fans are spread across multiple platforms, broadcasters risk losing negotiating power with advertisers,” she said. “The key will be interoperability and standardised data sharing protocols.”
The European Union’s Digital Services Act (DSA) has also come under scrutiny, as it imposes stricter data‑privacy requirements that could impact Indian startups that rely on user data for analytics. SEBI’s upcoming guidelines on digital payments in sports will further shape the regulatory landscape.
Investor Takeaways
Investors are taking away a few hard lessons:
1. Revenue Models Matter – Founders who can demonstrate a clear path to monetisation, whether through micro‑subscriptions, data licensing, or ticketing fees, are more likely to secure capital.
2. Regulatory Alignment Is Crucial – Companies that navigate SEBI’s regulations and align with the DSA are positioned for long‑term success.
3. Strategic Partnerships Add Value – Tie‑ups with UEFA, IFA, and broadcasters can provide credibility and a built‑in user base, reducing customer acquisition costs.
4. Valuation Discipline – Over‑valuation can lead to funding failures, as seen with PlayPulse. Investors now favour companies with realistic growth projections and a solid balance sheet.
According to a recent note from Morgan Stanley, the sports‑tech sector’s average valuation multiple has dropped from 18× in 2022 to 12× in 2024, reflecting a shift toward more conservative pricing.
Potential Risks
Regulatory Headwinds
The RBI’s potential tightening of digital payment norms could raise transaction costs, impacting micro‑subscription models. SEBI’s scrutiny of blockchain ticketing may delay or even halt the rollout of such platforms, affecting companies like FanChain.
“The PlayPulse debacle is a wake‑up call: without a clear monetisation path, even the most promising sports‑tech startups can falter in India’s competitive market.”
Market Saturation
With over 30 sports‑tech startups now operating in India, the market could become saturated. Only a handful will survive, and the rest may be absorbed or shut down, leading to a “creative destruction” phase that could deter new entrants.
Data Privacy Concerns
The DSA’s stringent data‑privacy rules could limit the amount of user data that Indian firms can collect and analyse, hampering the development of sophisticated analytics platforms.
Economic Slowdown
A slowdown in India’s GDP growth could reduce discretionary spending on sports subscriptions and merchandise, affecting revenue streams for firms like GoalStream.
Looking Ahead
The next few months will be telling. UEFA’s upcoming 2025‑26 Europa League season will feature a new licensing model that allows Indian broadcasters to bundle multiple competitions, potentially increasing revenue per viewer. If Indian sports‑tech firms can secure data‑sharing agreements under this model, they could unlock new monetisation channels.
Meanwhile, the RBI’s upcoming consultation
💡 Key Statistic
The UEFA Europa League has seen a 27% increase in Indian viewership over the past year, translating to an estimated ₹3.5 billion in advertising revenue.
The Editorial Bottom Line
While PlayPulse’s funding failure underscores the volatility of India’s sports‑tech scene, the UEFA Europa League’s rising popularity offers a beacon of opportunity. Startups that can marry data analytics with localized fan experiences will likely steer the next wave of growth.
Frequently Asked Questions
Why did PlayPulse’s funding round fail?
The investors demanded a 30% equity stake, which the founders could not justify given the company’s valuation and growth trajectory. This mismatch led to the deal’s collapse.
How does the UEFA Europa League reach Indian audiences?
Through digital streaming platforms, localized commentary, and targeted social media campaigns, the league has expanded its reach, boosting viewership by 27% in the last year.
What monetisation models are most effective for sports‑tech in India?
Subscription tiers, micro‑transactions for in‑game content, and data‑driven advertising are proving most effective, as they align revenue with fan engagement levels.
What should new sports‑tech startups focus on to succeed?
They should prioritize user data analytics, localised content, and flexible pricing models that cater to India’s diverse fan base, ensuring sustainable revenue streams.