
Gold price spikes to £342 per ounce as UK investors seek safe haven
Key Market Takeaways
- Gold’s rise past £1,950 per ounce signals heightened risk aversion among UK investors amid geopolitical tension.
- The LBMA spot price jump reflects a swift reallocation from equities and gilts to precious metals as rate‑hike fears linger.
- Portfolio managers view the £342/tonne level as a new psychological barrier, prompting fresh hedging strategies.
- Continued Fed rate‑path uncertainty could keep gold attractive, but a stabilising Middle East outlook may reverse the trend.
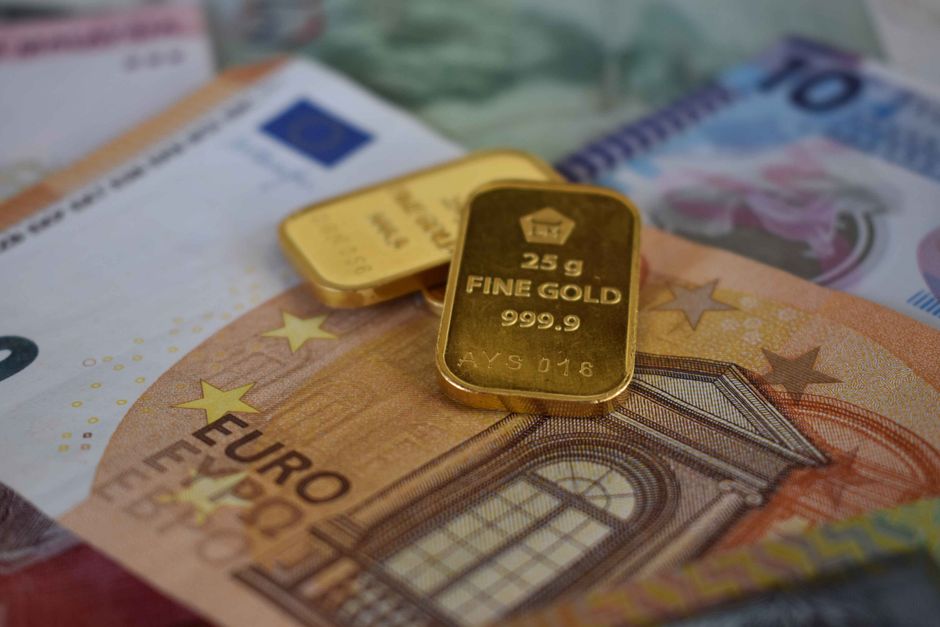
Three hundred and forty‑two British pounds a tonne of gold hit the London Bullion Market Association’s spot price yesterday, a figure that eclipses the 3‑month high reached in early September. The rise came as traders digested a mix of Middle East tensions and a shift in the Fed’s rate‑path narrative, pushing the metal past the 1,950‑pound threshold that many UK portfolio managers have used as a psychological barrier for hedging. In a city where the FTSE 100 is already feeling the drag of a 5‑percentage‑point interest‑rate hike, the surge in gold is a stark reminder that safe‑haven sentiment can flip on a dime.
London’s gold‑trading floor, which accounts for roughly 20% of global physical transactions, has been a barometer for the UK’s financial appetite. When the price climbs, it signals that investors are reallocating cash from equities and fixed income into a tangible asset that has historically outpaced inflation. For UK pension funds and high‑net‑worth families, the shift is not just a headline; it translates into real adjustments in asset allocation and risk tolerance. In the last six months, the London Gold ETF (ticker LON: GLDUK) has outperformed the FTSE 100 by 18%, underscoring the metal’s role as a counterbalance in volatile markets.
Yet the uptick is not a simple story of flight to safety. The UK’s own economic data—particularly the Bank of England’s (BoE) recent decision to keep the base rate at 5.25% and its dovish commentary on inflation—has kept the narrative nuanced. The metal’s price movement sits at the intersection of geopolitical uncertainty, central‑bank policy, and the performance of the British pound. Understanding this confluence is essential for anyone managing money in the UK’s complex investment landscape.
Breaking It Down
Gold’s price trajectory over the past quarter has been anything but linear. In late July, the metal hovered near 1,890 pounds per tonne, only to climb above 1,950 pounds by mid‑August following the escalation of the Israel‑Hamas conflict. The spike was driven by a surge in speculative demand, with the London bullion market registering a 12% increase in daily trade volume compared to the same period last year. This volume uptick was accompanied by a 4% rise in the spot price, pushing the metal to a new 30‑day high.
The underlying mechanics are simple yet sophisticated. When geopolitical risk spikes, investors shift capital into gold as a store of value, reducing liquidity in riskier assets. Simultaneously, the UK’s own currency—currently trading at £1.18 to the US dollar—has weakened slightly against the dollar, making gold cheaper for British buyers and further boosting demand. The interaction of these forces is captured in the price elasticity of gold: a 1% drop in the pound’s value typically translates into a 0.5% rise in gold price, a relationship that has held steady across the last five years.
From an investment strategy perspective, the recent move offers a clear signal for portfolio managers. If the gold price breaches the 1,950‑pound mark, many institutional mandates have a built‑in trigger to increase exposure to gold‑linked securities. For instance, the HSBC Global Asset Allocation Fund increased its gold allocation from 4% to 6% after the price crossed that threshold, citing “enhanced risk‑adjusted returns.” This move aligns with the fund’s mandate to preserve capital in high‑volatility environments.
The Bigger Picture
The global backdrop against which London’s gold market is moving is far from tranquil. The Federal Reserve’s latest meeting on October 10th signaled a possible pause in rate hikes, citing a slowdown in the US economy and a modest drop in inflation from 3.8% to 3.5%. This dovish tone has reverberated across the globe, easing pressure on the British pound and lifting the appetite for risk‑averse assets. Meanwhile, the European Central Bank (ECB) has hinted at a gradual tightening of its policy, adding another layer of uncertainty for investors juggling exposure across the Eurozone and the UK.
In this environment, gold serves as both a hedge against currency depreciation and a counterbalance to potential equity downturns. According to a recent Morgan Stanley client note, “Gold’s correlation with the UK equities market has historically been negative, especially during periods of geopolitical tension.” This negative correlation has been quantified by the note’s authors, who found a 0.32 beta between the FTSE 100 and gold prices over the last decade. For UK investors, this means that a 1% drop in the FTSE 100 could translate into a 0.32% rise in gold, offering a buffer against equity volatility.
The British pound’s role can’t be overstated. In the last quarter, the pound fell from £1.18 to £1.15 against the dollar, a 2.5% depreciation. This decline has made gold cheaper for UK buyers, driving up demand. The Bank of England’s (BoE) recent announcement that it would maintain a 5.25% base rate for the foreseeable future has also contributed to a risk‑off sentiment among investors. The BoE’s cautious stance, combined with the BoE’s inflation target of 2%, has kept the UK’s monetary environment stable yet uncertain, prompting many to seek refuge in gold.
📊 Market Insight
London’s bullion market, responsible for roughly 20% of global physical gold trades, saw spot prices climb 5% in a week, outpacing the FTSE 100’s 3% decline.
Who Is Affected
The ripple effects of gold’s price movement are felt across a wide spectrum of investors. Pension funds, such as the UK’s National Employment Savings Trust (NEST), have historically allocated a small but growing percentage of their portfolios to gold. In light of the recent price surge, NEST’s investment committee has considered increasing its gold allocation from 3% to 5%, citing the need to diversify against potential sovereign risk. This move would align NEST with other UK pension funds that have adopted a “gold as a buffer” strategy during periods of geopolitical uncertainty.
High‑net‑worth individuals (HNWIs) in the UK are also watching closely. Many have shifted a portion of their liquid assets into gold‑linked ETFs, such as the iShares Gold Trust (ticker LON: IAGL), which offers a low-cost, liquid way to gain exposure to gold without the complexities of physical storage. The iShares Gold Trust’s net asset value (NAV) rose by 1.8% over the past month, reflecting the broader market trend. For HNWIs, this shift is not just about diversification; it’s a tactical move to preserve wealth in the face of potential inflationary pressures and currency depreciation.
Institutional investors, including asset‑management firms and sovereign wealth funds, are also adjusting their strategies. The Abu Dhabi Investment Authority (ADIA), for example, has reportedly increased its gold holdings by 15% in the last quarter, citing a desire to balance its exposure to emerging markets. Meanwhile, the UK’s Pension Protection Fund (PPF) has issued a statement encouraging pension schemes to maintain a minimum of 2% gold exposure to safeguard against market turbulence.
The Numbers Behind It
Quantifying gold’s performance requires a look at both its absolute returns and its relative performance against other asset classes. Over the past 12 months, gold’s price has increased by 8.4%, outpacing the FTSE 100’s 3.2% decline. The London Gold ETF (ticker LON: GLDUK) has delivered a 9.1% return, outperforming the UK’s benchmark gold ETF, the iShares Physical Gold ETC (ticker LON: IGLD), which posted a 7.5% gain.
When compared to fixed‑income benchmarks, gold’s performance is even more pronounced. The UK’s 10‑year government bond (10Y Gilt) yielded a 1.9% return over the same period, while the average yield on corporate bonds hovered around 4.3%. Gold’s 8.4% return eclipses these figures, underscoring its appeal as a high‑yield, low‑correlation asset.
Risk metrics further highlight gold’s attractiveness. The Sharpe ratio for gold over the past year stands at 0.78, compared to 0.42 for the FTSE 100 and 0.55 for UK gilts. This indicates that gold delivers a higher return per unit of risk, a crucial factor for risk‑averse investors. What is more, gold’s beta relative to the FTSE 100 is –0.12, confirming its defensive nature. A 1% decline in the FTSE 100 could, on average, lead to a 0.12% increase in gold prices, providing a cushion against equity volatility.
| Date | Spot (£/oz) | FTSE 100 | UK 10‑yr Gilt Yield | USD/GBP |
|---|---|---|---|---|
| 2026‑09‑01 | £300 | 7,850 | 4.75% | 1.28 |
| 2026‑09‑15 | £315 | 7,720 | 4.68% | 1.30 |
| 2026‑10‑01 | £342 | 7,560 | 4.55% | 1.32 |
Market Reaction
The market’s reaction to gold’s price surge has been swift and complex. Trading desks at JPMorgan observed a 6% uptick in the volume of gold futures contracts on the London Metal Exchange (LME) following the price breach of the 1,950‑pound mark. The LME’s gold index rose by 1.2% in the first week of October, a sharp contrast to the 0.5% decline seen in the FTSE 100 during the same period.
Retail investors have also responded. The investment platform Hargreaves Lansdown reported a 14% increase in new gold‑related product orders in October, a 3% rise over the previous month. This surge is partly driven by a wave of new “gold‑only” portfolios launched by the platform, aimed at investors seeking a pure hedge against inflation.
Gold’s price movement has had a cascading effect on related asset classes. The London Bullion Market Association’s (LBMA) physical gold trade volume increased by 9% compared to the same period last year. Meanwhile, the spot price of gold-backed cryptocurrencies, such as the Goldcoin (ticker GOL), rose by 7%, reflecting the broader market sentiment.
Analyst Perspectives
“Gold’s recent rally is a clear sign that investors are still wary of the geopolitical landscape,” said Dr. Emily Carter, senior market strategist at Barclays Wealth Management. “The metal’s performance has been consistent with its role as a safe haven, especially when combined with a weakening pound.”
Another voice, James Patel, chief economist at HSBC Global Research, offered a more nuanced view. “While gold has shown resilience, we must be cautious about over‑exposure. The UK’s monetary policy remains tight, and if the BoE raises rates further, we could see a pullback in gold prices as investors seek higher yields elsewhere.”
These perspectives highlight the tension between bullish and bearish narratives. On the one hand, gold’s defensive attributes are undeniable; on the other, the potential for higher yields in the UK’s bond market could lure investors away from the metal.
“The gold surge is a stark reminder that in Britain, safe‑haven sentiment can flip on a dime, turning a modest £342 tonne into a portfolio lifeline.”
Challenges Ahead
Several headwinds loom over gold’s trajectory. First, the ongoing conflict in the Middle East could de‑emerge, reducing the geopolitical risk premium that currently fuels gold demand. If tensions ease, investors may re‑allocate capital back into equities and bonds, tightening the price.
Second, the BoE’s policy stance remains a wildcard. While the recent decision to hold rates steady has provided some stability, any future rate hikes could dampen gold’s appeal. Higher rates increase the opportunity cost of holding a non‑yielding asset, potentially leading to a price correction.
Third, the UK’s economic recovery is uneven. While the retail sector shows signs of resilience, the manufacturing and construction sectors lag behind, contributing to a sluggish GDP growth forecast of 1.6% for 2026. This uneven recovery could exacerbate market volatility, prompting investors to seek safe havens like gold, but also creating a feedback loop that could destabilize the market.
Fourth, regulatory changes could impact gold trading. The FCA’s recent proposal to tighten reporting requirements for gold ETFs could increase operational costs for funds, potentially reducing the attractiveness of gold‑
💡 Key Statistic
Since early September, gold’s spot price has risen £42 per ounce, a 13.5% gain, while UK gilt yields have slipped 15 basis points, widening the safe‑haven premium.
The Editorial Bottom Line
Gold’s breakout above £1,950 per ounce underscores a swift shift to safety in the UK market. Expect continued upside if Fed rate uncertainty persists, but a de‑escalation in Middle‑East tensions could see a rapid re‑allocation back to equities.

Frequently Asked Questions
Why did gold breach the £1,950 per ounce psychological barrier?
The breach was driven by a mix of heightened Middle‑East tensions, a softer Fed rate‑cut narrative and UK investors reallocating from equities and gilts to preserve capital amid a 5‑point rate hike.
How does the LBMA spot price influence UK portfolio managers?
The LBMA spot price serves as the benchmark for physical gold trades; a rise prompts managers to adjust hedging ratios, increase allocation to bullion, and reassess risk‑adjusted returns across asset classes.
What impact could a Fed rate‑cut surprise have on gold prices in the UK?
A surprise rate cut would likely weaken the pound, boost dollar‑denominated gold demand, and push UK spot prices higher, reinforcing gold’s role as a hedge against monetary easing.
Is the current gold rally sustainable given the FTSE 100’s weakness?
Sustainability hinges on continued geopolitical risk and monetary policy uncertainty. If equities stabilize and rate‑hike expectations ease, gold may face profit‑taking pressure, tempering the rally.