
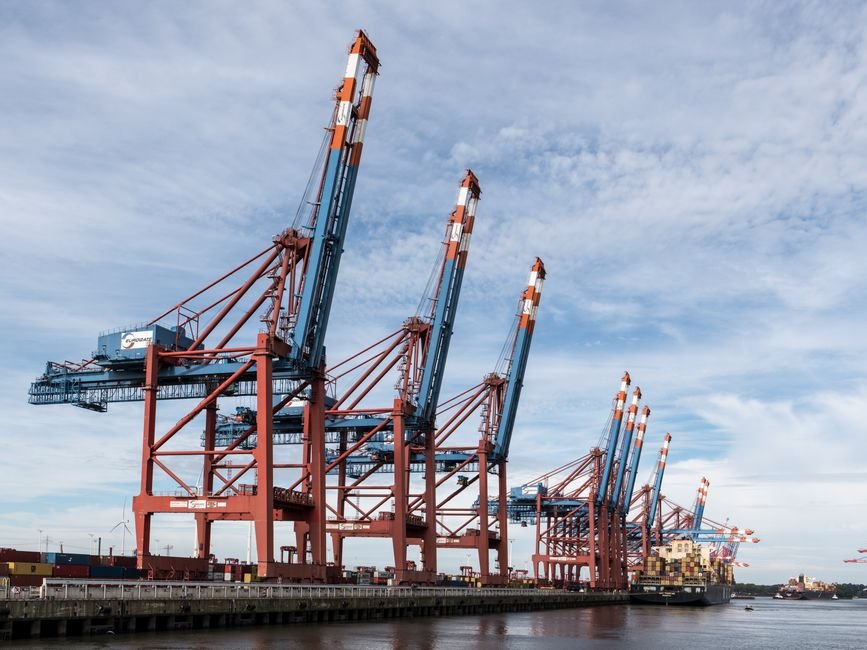
US Trade Deficit And Import-Export Policy Changes — Analysis and Market Outlook
Key Takeaways
- Significant market developments around US Trade Deficit and Import-Export Policy Changes are creating new opportunities and risks.
- Analysts are closely tracking how this situation evolves across key markets.
- Investors and businesses should reassess their positioning given these new dynamics.
- Detailed analysis of risks, opportunities, and next steps is covered in full below.
The United States posted a persistent trade deficit in the most recent reporting period, a condition that has drawn renewed attention from policymakers and investors alike. Data released by the U.S. Census Bureau indicated that imports continued to outpace exports across a broad range of goods and services, a pattern that has shaped the macro‑economic backdrop for equity, fixed‑income, and currency markets. At the same time, the administration has signaled a shift in its import‑export policy framework, emphasizing strategic supply‑chain resilience, targeted tariff adjustments, and expanded trade‑promotion initiatives. The convergence of a sizable deficit and evolving policy tools creates a complex environment for market participants seeking to position portfolios amid shifting trade flows and regulatory signals.
What Is Happening
The latest quarterly figures show that the United States imported more merchandise than it exported, widening the gap that has been a feature of the post‑2008 economic landscape. While the deficit remains a headline number, the composition of trade flows has evolved. High‑technology components, automotive parts, and certain consumer goods have contributed to a robust import tally, whereas services such as financial and intellectual‑property‑related exports have shown relative strength. The administration’s recent trade agenda, outlined in a series of memoranda and interagency briefings, focuses on reducing reliance on single‑source suppliers for critical inputs, adjusting tariff structures for specific product categories, and negotiating bilateral agreements that aim to open new markets for U.S. manufacturers.
Simultaneously, the Department of Commerce has launched a set of export‑promotion programs that target emerging sectors, including clean‑energy technology, advanced manufacturing, and digital services. These initiatives are coupled with a modest recalibration of existing tariffs on select consumer goods, intended to alleviate pressure on downstream industries without compromising broader protectionist objectives. The policy shift reflects a balancing act: preserving the competitive edge of domestic producers while addressing the fiscal and balance‑sheet implications of a sustained deficit.
The Core Story
At its core, the current situation reflects the interaction between three interrelated dynamics: a structural imbalance in the trade ledger, a policy response that seeks to reshape supply‑chain dependencies, and the market’s interpretation of these moves in terms of risk and return. The trade deficit, by definition, represents an excess of import spending over export earnings. Over the past decade, the United States has run a deficit that consistently exceeded $600 billion annually, according to official statistics. This macro‑level imbalance has implications for the value of the U.S. dollar, the pricing of Treasury securities, and the earnings outlook for export‑oriented corporations.
The policy response is anchored in a strategic assessment of national security and economic competitiveness. The administration’s emphasis on “critical minerals,” “semiconductor supply chains,” and “domestic manufacturing capacity” signals a willingness to intervene in markets that were previously left to market forces. Adjustments to tariffs on certain consumer electronics and automotive parts illustrate a calibrated approach: reducing barriers where domestic production can be quickly scaled, while maintaining higher duties on goods deemed less essential to strategic objectives.
Investors have responded to these developments by re‑evaluating exposure to sectors directly impacted by trade policy. Companies with significant import costs, such as automotive assemblers and consumer‑electronics manufacturers, have seen analysts adjust earnings forecasts to reflect potential cost savings from tariff reductions. Conversely, exporters in aerospace, software, and financial services have attracted attention for their ability to capture a larger share of global demand as the United States seeks to expand market access through new agreements.
Why This Matters Now
The timing of the policy adjustments aligns with several macro‑economic headwinds that heighten the relevance of trade dynamics. Inflationary pressures have prompted the Federal Reserve to maintain a restrictive monetary stance, influencing capital flows and the relative attractiveness of the dollar. A stronger dollar typically exacerbates the trade deficit by making imports cheaper and exports more expensive. The administration’s moves to support export growth and mitigate import cost pressures can be viewed as an effort to counterbalance currency‑induced distortions.
Additionally, geopolitical tensions have reshaped global supply‑chain configurations. Restrictions on technology transfers to certain jurisdictions and sanctions on specific entities have forced multinational firms to reconsider sourcing strategies. The United States’ focus on diversifying supply sources, particularly for components such as advanced chips and rare‑earth elements, creates investment opportunities in domestic producers and allied partners. Investors monitoring the trade deficit therefore need to factor in not only the headline balance but also the underlying shifts in where and how goods are sourced.
From a fiscal perspective, the trade deficit contributes to the broader current‑account deficit, which in turn influences the Treasury’s borrowing requirements. A larger deficit can increase the supply of Treasury securities, potentially affecting yields and the risk premium demanded by investors. Policy actions that aim to narrow the trade gap, even modestly, could alleviate some upward pressure on yields, thereby impacting fixed‑income portfolios.

Key Forces at Play
Two principal forces shape the evolving trade landscape: policy‑driven supply‑chain restructuring and global demand elasticity. The first force is evident in the administration’s emphasis on “onshoring” and “friendshoring.” By incentivizing domestic production of critical components, the government hopes to reduce exposure to foreign disruptions. This approach has prompted several large manufacturers to announce capital expenditures for new facilities in the Midwest and the South, targeting sectors such as battery production and semiconductor fabrication. The capital allocation decisions of these firms have immediate implications for equity markets, particularly for construction, industrial equipment, and raw‑material suppliers.
The second force concerns the responsiveness of foreign markets to U.S. export initiatives. The United States has entered negotiations aimed at expanding market access for services and high‑value goods in regions such as Southeast Asia and Latin America. The success of these talks hinges on the ability of U.S. firms to meet foreign standards, price competitiveness, and the political willingness of partner nations to reduce non‑tariff barriers. The degree to which these negotiations translate into measurable export growth will affect the earnings trajectories of firms heavily reliant on overseas sales.
A third, more subtle force relates to investor sentiment toward the trade deficit as a signal of economic health. Some market participants interpret a widening deficit as a sign of robust domestic demand, while others view it as a vulnerability that could erode the dollar’s value. The divergent interpretations create a spectrum of pricing for assets that are sensitive to exchange‑rate movements, such as multinational corporations and commodities priced in dollars.
Regional Impact
The United States’ trade policy adjustments have reverberated across several regions, each experiencing distinct effects. In the Midwest, where automotive assembly plants dominate, reductions in tariffs on certain auto parts have lowered input costs, potentially improving operating margins for manufacturers that export finished vehicles. In the South, incentives for renewable‑energy component production have attracted firms specializing in solar‑panel manufacturing, aligning with the broader national push toward clean‑energy infrastructure. The Pacific Northwest, home to a concentration of semiconductor firms, stands to benefit from subsidies and tax credits aimed at expanding chip‑fabrication capacity, a sector directly linked to the strategic importance placed on advanced technology supply chains.
Internationally, Mexico and Canada, as members of the United States‑Mexico‑Canada Agreement (USMCA), have seen adjustments to rules of origin that could affect cross‑border automotive trade. The United States’ focus on increasing domestic content in certain products may shift the balance of trade within the trilateral framework, prompting Canadian and Mexican firms to adapt their sourcing strategies. In East Asia, the United States’ emphasis on “friendshoring” has led to deeper engagement with allies such as Japan and South Korea, particularly in the realm of semiconductor collaboration. These partnerships may redirect some import volumes away from other sources, reshaping regional trade patterns.
In Europe, the United States’ renewed push for service‑sector exports aligns with the strong demand for American financial and software services, potentially enhancing the trade surplus in those categories. However, the impact of any tariff modifications on European agricultural products remains limited, given the existing structure of trade agreements and the relatively small share of such goods in the overall deficit.
What the Experts Say
Analysts at major financial institutions have highlighted the nuanced implications of the policy shift. One senior economist noted that the administration’s targeted tariff reductions could provide immediate cost relief for firms with high import exposure, while the broader strategic emphasis on supply‑chain resilience may take several years to materialize fully in trade statistics. A fixed‑income strategist observed that any measurable narrowing of the trade deficit could modestly ease upward pressure on Treasury yields, though the effect would be contingent on concurrent fiscal and monetary developments.
Trade scholars have pointed out that the United States’ approach represents a hybrid of traditional protectionism and modern industrial policy. By focusing on sectors deemed essential for national security, the policy avoids a blanket increase in barriers that could provoke retaliatory measures, yet it still leverages tariff tools to influence market behavior. A professor of international economics emphasized that the success of these measures will depend on the ability of domestic firms to scale production quickly enough to meet existing demand without generating excess capacity.
Risks and Opportunities
Investors must weigh a set of intertwined risks and opportunities as the United States navigates its trade deficit and policy adjustments. On the risk side, the possibility of retaliatory measures from trading partners remains a concern. While the administration has sought to limit tariff changes to specific categories, any perceived protectionist tilt could trigger counter‑tariffs, particularly in sectors such as agriculture and automotive components. Such developments could compress margins for exporters and elevate input costs for import‑dependent manufacturers.
Another risk involves execution uncertainty in domestic capacity expansion. Incentive programs aimed at onshoring critical components require significant capital outlays, skilled labor, and regulatory approvals. Delays or cost overruns could diminish the anticipated benefits, leaving firms exposed to continued import reliance. Moreover, the exchange‑rate environment adds a layer of volatility. A stronger dollar, sustained by monetary policy, could offset gains from tariff reductions by making U.S. exports less price‑competitive abroad.
Opportunities arise from sectoral realignment driven by policy incentives. Companies positioned to supply the domestic market with critical inputs—such as rare‑earth miners, battery manufacturers, and advanced‑material producers—stand to benefit from heightened demand and potential subsidies. Equity investors may find attractive entry points in firms that have already secured government contracts or are part of public‑private partnerships targeting supply‑chain security.
For fixed‑income investors, the interplay between trade balance dynamics and Treasury issuance presents a nuanced landscape. A modest improvement in the trade deficit could temper the growth rate of Treasury supply, supporting price stability in longer‑duration bonds. Conversely, if policy changes fail to narrow the deficit, continued fiscal deficits may pressure yields higher, creating relative value opportunities in shorter‑duration instruments.
Currency traders can exploit dollar volatility linked to trade developments. If the administration’s actions are perceived as successful in reducing the deficit, the dollar may weaken relative to peers, benefitting commodity exporters and multinational firms with earnings denominated in foreign currencies. Conversely, a failure to achieve measurable progress could reinforce a risk‑off narrative, bolstering the dollar’s safe‑haven appeal.

What to Watch Next
The trajectory of the United States’ trade deficit will be illuminated by several upcoming data releases and policy milestones. The quarterly trade balance report from the Census Bureau, scheduled for release in the next month, will provide the first hard look at how recent tariff adjustments have impacted import volumes. Analysts will scrutinize the breakdown by sector to assess whether targeted reductions have translated into measurable cost savings for affected industries.
Legislative activity in Congress will also shape the investment landscape. Bills proposing additional funding for domestic semiconductor fabs, or extending tax credits for renewable‑energy equipment, could accelerate onshoring trends. The progress of ongoing trade negotiations with key partners—particularly the United Kingdom, Japan, and the Association of Southeast Asian Nations—will indicate the likelihood of expanded market access for U.S. services and high‑technology goods.
A further point of focus will be the Federal Reserve’s policy path. Should inflation pressures ease and the central bank pivot toward a more neutral stance, the dollar could experience a moderation that would affect trade‑related pricing dynamics. Conversely, a continuation of a tight monetary regime would sustain a strong dollar, potentially deepening the deficit unless offset by policy‑driven export growth.
Investors should also monitor corporate earnings disclosures for clues about how firms are adapting to the new policy environment. Companies that report lower import‑cost burdens or higher export revenues may serve as leading indicators of the effectiveness of the administration’s approach. Conversely, firms that cite supply‑chain bottlenecks or unexpected tariff exposures will highlight areas where policy objectives have yet to materialize.
Finally, geopolitical developments—such as sanctions regimes, diplomatic negotiations, and regional conflicts—will continue to influence the broader trade architecture. Any abrupt changes in the global risk environment could reshape the demand for U.S. goods and services, thereby affecting the trade deficit in ways that are difficult to forecast.
In sum, the United States’ trade deficit and the evolving import‑export policy framework present a multifaceted set of considerations for investors. The balance between strategic supply‑chain resilience, targeted tariff adjustments, and the pursuit of new export markets creates both